A CFO’s guide to evaluating scope, savings evidence, internal effort, execution, and follow-through for effective spend management before committing to a cost-reduction engagement.
A cost-reduction engagement can uncover significant savings or produce another report that never makes its way to the bottom line.
Before committing, CFOs need clear answers on scope, evidence, internal effort, execution, and follow-through. Together, these questions reveal what the provider is actually committing to deliver, what the client will need to contribute, and how clearly the engagement connects identified opportunities to financial results.
The stakes are significant. McKinsey’s 2025 research on procurement-led transformation found that procurement typically accounts for more than 20% of a transformation’s total financial impact. Its analysis of more than 340,000 transformation initiatives, collectively representing over $200 billion in spend, also found that companies achieving their procurement savings targets are nearly twice as likely to achieve their broader business-wide savings targets.
For a CFO, that makes the engagement itself worth scrutinizing. For example, a consultant can identify $500,000 in potential savings, but that figure means little until Finance knows how it was calculated, what baseline supports it, what portion is actually recoverable or reducible, and who will turn the opportunity into a financial result.
That distinction is easy to overlook when evaluating cost reduction consulting. A benchmark is not a negotiated reduction. An identified billing error is not a recovered overpayment. And a projected opportunity is not a saving that reaches the P&L.
They also show whether the engagement can strengthen spend management by giving Finance clearer visibility into the costs, vendors, and billing practices that require attention.
Here are five questions worth asking before starting a cost reduction consulting engagement.
- What exactly is included in the engagement and what isn’t?
- How will you prove that the savings are real?
- How much time and work will this require from my team?
- Who will turn identified savings opportunities into actual results?
- What happens after the savings are identified?
What does a cost reduction consultant actually do?
A cost reduction consultant analyzes operating expenses, contracts, invoices, and vendor charges to identify opportunities to lower costs or recover overpayments. Depending on the engagement, the consultant may also benchmark pricing, negotiate with vendors, support corrective action, and strengthen spend management.
1. What Exactly Is Included in the Engagement and What Isn’t?
What it is
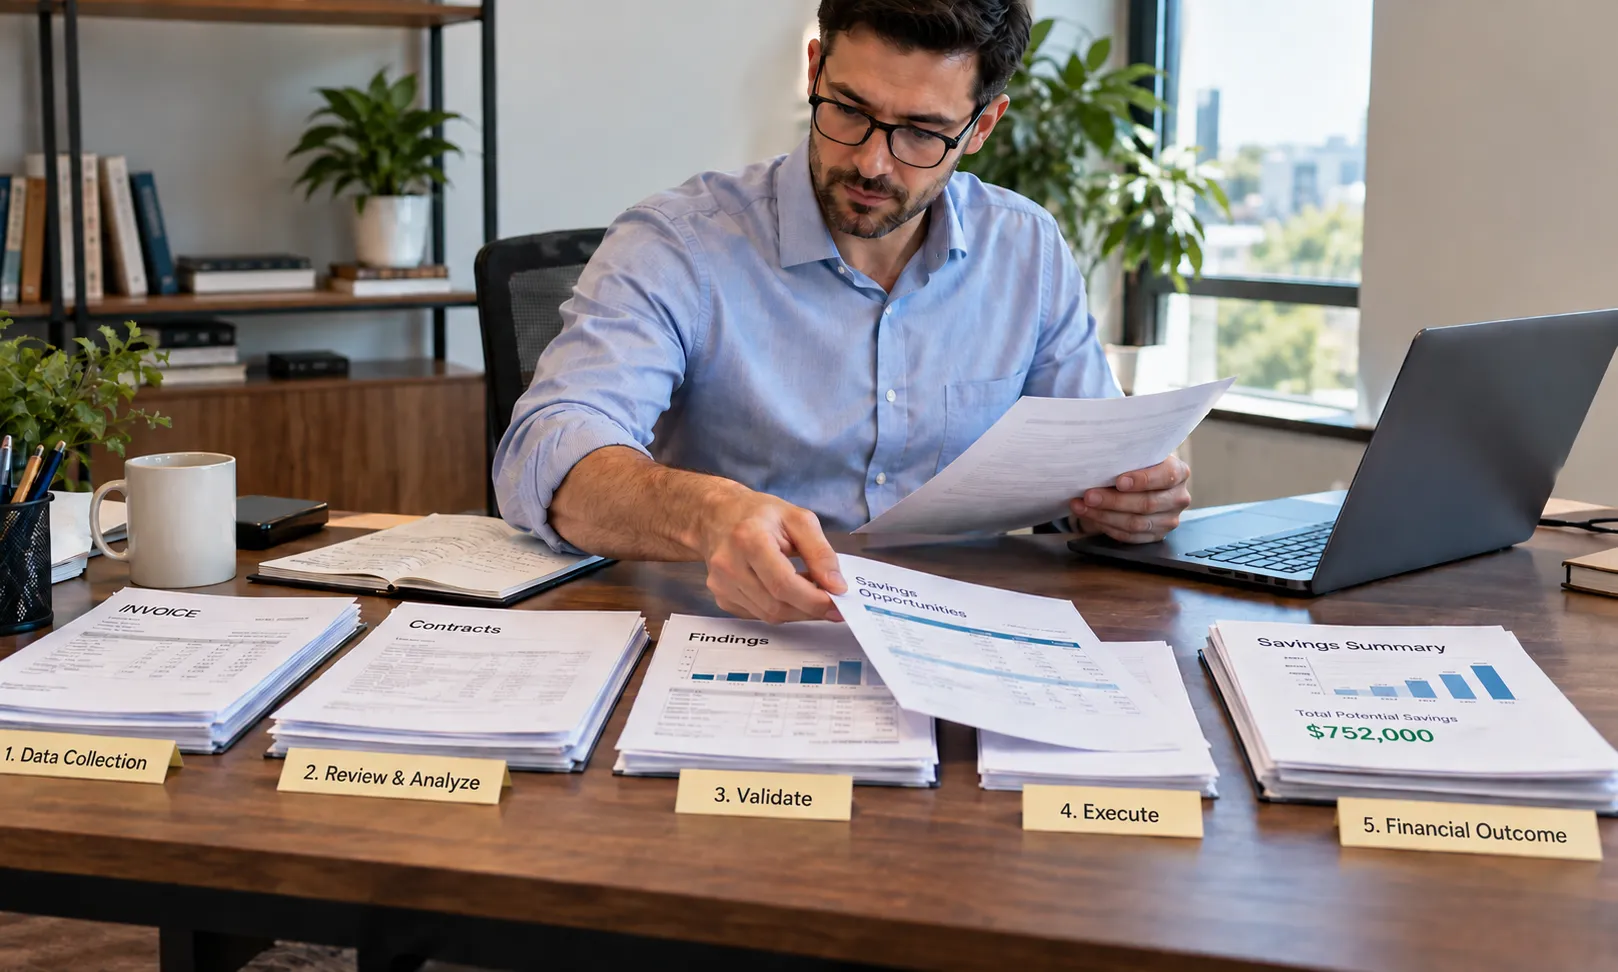
This is the scope question: What exactly will the cost reduction consulting provider review, deliver, execute, and charge for, and where does the client’s responsibility begin? A proposal can sound comprehensive while covering only the analysis itself, particularly when a company has multiple locations, vendors, contracts, and invoice streams to review.
An experienced CFO should distinguish between the scope of review and the scope of execution. Reviewing invoices, identifying an overcharge, validating the finding, negotiating a correction, and confirming the financial result are separate deliverables, not one activity.
CFOs should also look beyond the number of spend categories included. A broad scope does not necessarily mean deep category expertise. Ask who will review each category, what category-specific experience they bring, and whether they understand the pricing structures, fees, contracts, and vendor practices that can drive overspending within it.
That distinction is also important for spend management. Finance needs to know whether the engagement is designed to improve spend management visibility into a specific cost category or address the underlying issue through corrective action.
If the proposal does not make those boundaries clear, the headline scope may sound broader than what the CFO is actually buying.
Why Does It Matter?
- Clarifies which spend categories, analyses, deliverables, and outcomes are actually covered by the cost reduction consulting engagement
- Establishes a clear basis for comparing cost reduction consulting providers without being distracted by different terminology or packaged service descriptions
- Exposes gaps between the consultant’s stated scope and the work your finance team may ultimately be expected to handle
- Tests whether broad service coverage is backed by genuine category-specific expertise
- Protects against unexpected fees when data collection, vendor discussions, implementation support, or follow-up analysis fall outside the agreed engagement
- Aligns finance, procurement, operations, and executive stakeholders around what the engagement is designed to accomplish
- Prevents a narrowly defined review from being mistaken for a broader spend management initiative covering expenses the consultant never agreed to evaluate
Real-World Example
Microflex, a 90-employee manufacturer generating approximately $27 million in annual sales, had waste, uniform and facility services, merchant card, parcel, and freight reviewed as part of its engagement. The review identified more than $752,000 in savings, showing why CFOs should define the categories and deliverables covered before work begins.
Pro tip: Map the engagement from data collection through financial outcome. For each stage, identify what the provider owns, what the client must provide, what constitutes completion, and whether additional fees apply.
2. How Will You Prove That the Savings Are Real?
What it is
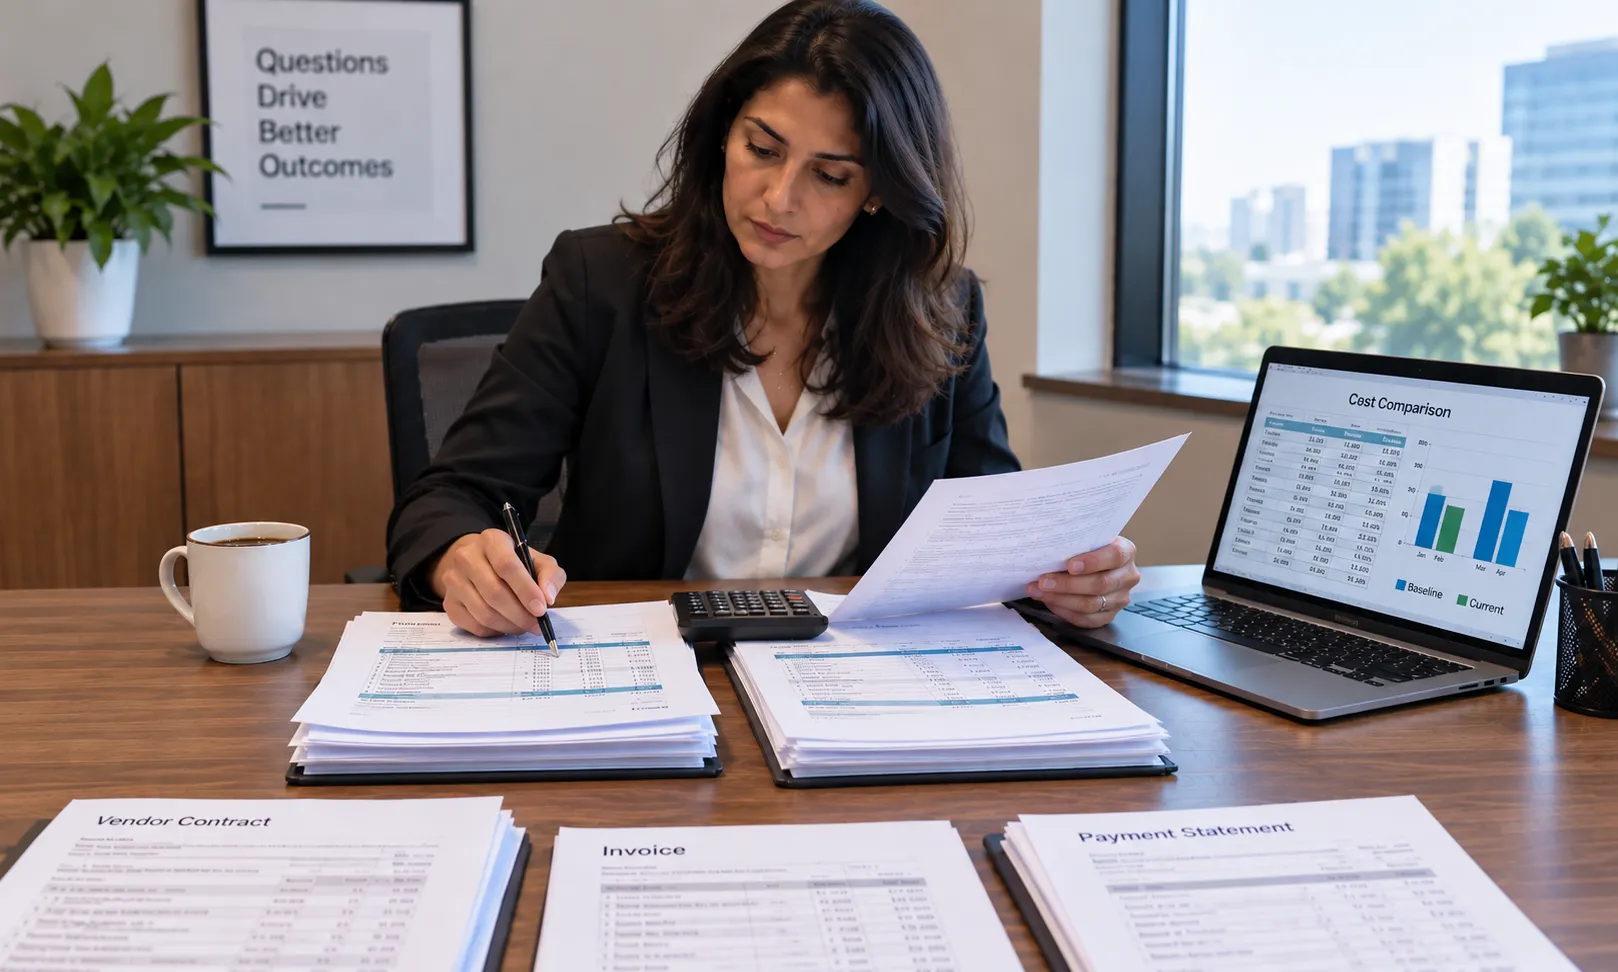
Once the scope of the cost reduction consulting engagement is clear, the next question is how the provider will substantiate the financial benefit. This is the measurement question. How does the provider distinguish an identified opportunity from a validated saving and, ultimately, a realized financial benefit? Those terms should not be treated as interchangeable.
An identified saving is a potential opportunity. A validated saving is an opportunity supported by invoices, contracts, statements, tax records, benchmarks, or another defensible baseline. For fragmented spend, that evidence may need to be traced across vendors, locations, contracts, and individual transactions rather than inferred from a high-level spend report.
The baseline matters, too. A lower future rate is different from an avoided price increase. A reduction in shipping spend caused by lower shipment volume is different from a reduction in the underlying freight rate. And a tax overpayment identified in historical records is a one-time recovery, not necessarily recurring annual savings.
For Finance, that evidence also makes spend management more actionable. It shows not just where money is being spent, but which rates, fees, contracts, or billing practices are driving the cost.
Therefore, CFOs should ask “How much can you save us?” and “What is the baseline, what changed, and what evidence establishes the benefit as realized?”
What is the difference between cost savings and cost avoidance?
Cost savings reduce an existing cost against a defined baseline, while cost avoidance prevents a future increase or expense from occurring. The distinction matters in cost reduction consulting because an avoided price increase can improve financial performance without reducing the company’s current spend.
Why Does It Matter?
- Separates potential opportunities from validated and realized financial benefits
- Establishes a defensible baseline for measuring actual improvement
- Distinguishes recurring savings from one-time recoveries and refunds
- Exposes whether apparent savings are driven by lower rates, reduced volume, avoided increases, or other factors
Real-World Example
At automotive-parts manufacturer Newman Technology, a review spanning waste, uniform and facility services, merchant card, parcel, and freight identified more than $1.3 million in savings, including recurring annual savings. The breadth of the review illustrates why CFOs should ask how a provider arrives at its savings figure and which opportunities are expected to produce ongoing financial benefit.
Pro tip Ask the provider to show one savings calculation from start to finish, including the baseline, calculation, supporting documentation, assumptions, and whether the resulting benefit is one-time, recurring, or an avoided increase. This gives Finance a more reliable foundation for spend management decisions than a projected savings figure alone.
3. How Much Time and Work Will This Require From My Team?
What it is
After understanding how the savings will be measured, the next consideration is what it will take from your business to get there. This is the resource question. How much internal time and effort will the engagement require from the business? The real question is not simply what the consultant charges, but what the engagement will require from the business to produce the expected financial benefit.
Cost reduction consulting fees are visible; internal labor often is not. Finance may need to gather invoices, answer recurring data requests, validate findings, join vendor discussions, approve changes, or coordinate implementation across Procurement, AP, Operations, and Accounting.
For a finance team already balancing close, forecasting, reporting, spend management, and other competing priorities, those requirements can materially affect the economics of the engagement.
That creates an important distinction between gross savings and the net financial benefit of pursuing them. A $200,000 opportunity does not have the same economic value if capturing it requires hundreds of internal hours, vendor spend management, implementation costs, or operational disruption.
The objective is not simply to find a large savings number. It is to determine whether the financial benefit justifies the total effort and resources required to capture it. For Finance, the same analysis can also improve spend management discipline by making the internal resources required to pursue an opportunity visible.
Why Does It Matter?
- Preserves finance-team capacity for closing, forecasting, reporting, spend management, and other responsibilities that cannot be put on hold for a cost reduction consulting engagement
- Reduces disruption when the consultant takes responsibility for data gathering, invoice analysis, contract reviews, site visits, or other heavy-lift activities
- Limits the hidden internal cost of pursuing savings that appear attractive on paper but require substantial employee time to uncover and validate
- Accelerates the cost reduction consulting engagement when responsibilities, information requirements, and internal points of contact are clear from the beginning
- Improves spend management accountability by making the client’s actual workload visible rather than treating internal participation as an afterthought
Real-World Example
Midland Farms, a $20 million dairy company with 89 employees, had more than $254,000 in savings identified across waste, Sales/Use Tax, and utility expenses. Despite the breadth of the review, total client involvement amounted to only a few hours, illustrating why CFOs should evaluate an engagement based on the internal effort required, not simply the potential savings.
Pro tip Ask for a client-side responsibility map before the engagement starts. If the provider cannot explain what your team will need to supply, review, approve, negotiate, or implement, the true internal cost of the engagement is still unclear.
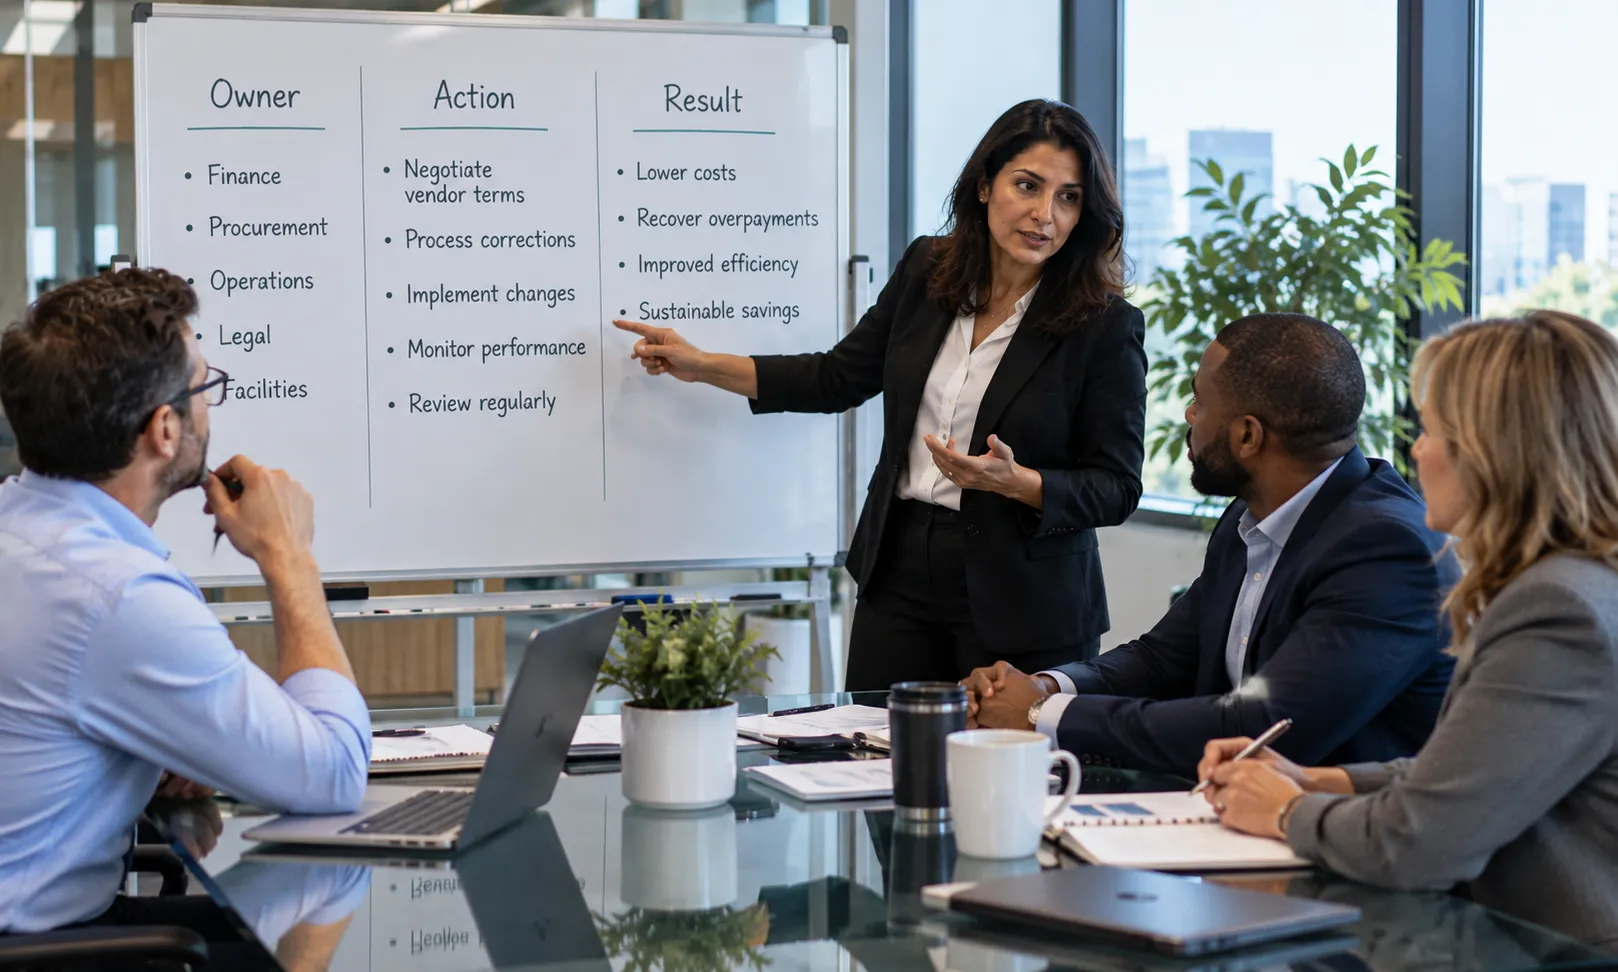
4. Who Will Turn Identified Savings Opportunities Into Actual Results?
What it is
Once the internal commitment is clear, the next question is who will actually move the identified opportunities forward. This is the execution and accountability question. Who moves an identified opportunity from analysis toward an actual financial result?
Cost reduction consulting engagements can stop at different points. One provider may identify and document an opportunity; another may benchmark rates, communicate with vendors, negotiate terms, coordinate corrective action, or support the client through implementation.
Neither model is inherently wrong. The problem is assuming that identifying an opportunity means capturing the savings. Before the engagement begins, a CFO should establish which actions the cost reduction consultant owns, which require client approval, and which remain with internal teams.
That distinction becomes especially important when savings depend on vendor negotiations, billing corrections, refunds, rate changes, or operational decisions. For Finance, effective spend management also depends on knowing what happens after an opportunity is identified: who acts, what changes, and what evidence confirms the result.
How can companies sustain cost savings over time?
Companies can sustain cost savings by documenting the change that produced the benefit, assigning ownership, monitoring the affected expense, and reviewing vendor rates or contracts when conditions change. Effective cost reduction consulting should leave Finance with enough visibility to recognize when savings begin to erode.
Why Does It Matter?
- Bridges the gap between identifying a cost reduction opportunity and realizing its financial impact
- Clarifies accountability for negotiations, corrections, refunds, vendor changes, rate adjustments, or other actions that may follow the analysis
- Prevents valuable findings from becoming another list of recommendations that remains unresolved after the consultant leaves
- Reduces execution delays when the cost reduction consulting provider has a defined role in moving findings toward resolution
- Strengthens the connection between analytical findings and measurable business outcomes
- Strengthens spend management visibility by showing what happens between the discovery of an opportunity and its potential impact on the company’s financial results
Pro tip For every material spend management opportunity, identify an owner, an action, and a definition of “realized.” An opportunity register that lists potential savings but has no accountable owner or next step is not an execution plan.
5. What Happens After the Savings Are Identified?
What it is
Even with an owner and an action defined, one final question remains: Where does the engagement actually end? This is the follow-through question. What is the engagement expected to accomplish with the savings, and where does the provider’s responsibility end? Not every benefit behaves the same way.
A historical tax recovery may be a one-time financial benefit, while correcting a freight rate, waste service level, merchant fee, or vendor contract can create recurring savings when the corrected terms remain in effect. Those benefits can change if rates increase, contracts renew, billing errors return, or operating requirements shift.
That is why “savings identified” should not automatically be treated as a financial benefit that will remain in effect. The engagement should leave the business with a clear record of what was recovered, what was changed, what remains to be implemented, who owns the remaining work, and what constitutes completion.
That record can also give Finance a more useful foundation for ongoing spend management oversight, particularly when the same vendor, contract, or billing issue affects multiple expenses.
Why Does It Matter?
- Preserves the value of the engagement by clarifying what happens to findings once the analysis is complete
- Prioritizes opportunities that require action while giving Finance a clearer view of items that may need additional validation or follow-through
- Improves spend management by showing where leakage originated and which underlying vendor, contract, process, or billing issues contributed to it
- Equips internal teams with practical knowledge they can apply when reviewing similar expenses and evaluating future cost reduction opportunities
Pro tip Define the “done” state for each benefit: refund received, invoice corrected, new vendor rate in effect, or contract amended. Match the definition to the type of benefit being pursued.
What to Evaluate Before Starting a Cost Reduction Consulting Engagement
Before starting a cost reduction consulting engagement, a CFO should know what the provider will review, how savings will be substantiated, what the internal workload will be, who owns execution, and what constitutes completion.
Key takeaways
- Define the engagement’s scope, deliverables, fees, and responsibilities before work begins.
- Require documented evidence that connects identified savings to actual financial data.
- Evaluate the amount of internal time and resources the engagement will consume.
- Establish who is responsible for moving identified opportunities toward financial results.
- Clarify what happens after the analysis so savings insights continue to inform spend management decisions.
Choose Cost Reduction Consulting With a Clear Path to Results
The right engagement should create a clear path from overlooked cost → verified opportunity → corrective action → measurable financial value.
For a CFO, that means evaluating the potential savings from cost reduction consulting as well as the evidence behind them, the work required from internal teams, who owns execution, and what happens after the analysis.
The SALT Group is built around this outcome-focused model. SALT provides performance-based, turnkey operating cost and expense reduction consulting with no upfront costs or hourly billing. Its consultants analyze targeted areas such as Sales & Use Tax, Freight & Parcel, Waste, Uniforms & Facilities, and Merchant Card Services at the invoice, contract, and transaction level to identify recoverable overpayments and ongoing cost-reduction opportunities.
SALT’s dedicated consulting teams bring an average of 24+ years of industry experience within their spend categories, while a dedicated Client Manager coordinates the engagement and minimizes the burden on internal teams. Depending on the category and opportunity, SALT can also support vendor discussions, corrective action, recovery, or implementation while keeping the client informed and involved where decisions are required.
The model is designed around outcomes: find the leakage, validate the opportunity, take the appropriate corrective action, and put measurable savings back on the bottom line.
See What a Cost Reduction Consulting Engagement Could Uncover
FAQs
1. How do I know whether a cost reduction consultant is worth the fee?
Look beyond the quoted fee. Evaluate the provider’s methodology, evidence behind projected savings, internal workload, execution support, and pricing model. A lower fee is not necessarily cheaper if your team must spend significant time managing the engagement or implementing recommendations. The key question is whether the cost reduction consulting engagement creates a credible path from identified opportunities to measurable financial results.
2. How much does cost reduction consulting cost?
There is no universal cost reduction consulting price because fees depend on the scope, categories reviewed, company complexity, and provider’s pricing model. Some firms charge hourly or fixed fees, while others use performance-based arrangements tied to identified or realized savings. When comparing providers, consider both the consulting fee and the internal resources required to support the engagement.
3. What should I expect my team to provide during a cost reduction consulting engagement?
The amount of client involvement can vary significantly by provider and scope. Some providers require clients to gather invoices, contracts, statements, and operational records, validate findings, or participate in vendor discussions. The SALT Group takes a turnkey approach, with its consultants coordinating information gathering and performing the review, while clients remain involved in necessary decisions and approvals. Before starting, ask the provider for a clear responsibility map so you understand what it will handle and what will remain with Finance, Procurement, AP, Operations, or other internal teams.
4. What happens if the savings identified cannot be implemented?
Not every identified opportunity automatically becomes a realized saving. Before starting a cost reduction consulting engagement, clarify which actions the consultant will handle, which require internal approval, and which remain with your team. Depending on the category, implementation may involve correcting billing, pursuing a refund, renegotiating vendor terms, adjusting service levels, or making internal changes. Establishing ownership upfront helps prevent valuable findings from becoming unresolved recommendations.
Capture More Savings With Smarter Cost Reduction Consulting
The right cost reduction consulting engagement should create a clear path from identified opportunities to measurable financial value. Use these five questions to evaluate the engagement before committing resources.
- Define the scope: Know what the provider will review, deliver, and execute.
- Verify the savings: Require evidence connecting claimed savings to financial data.
- Account for internal effort: Factor your team’s time into the engagement’s true cost.
- Assign execution ownership: Know who will move opportunities toward realized savings.
- Plan the follow-through: Clarify what happens to findings after the initial review.
The SALT Group’s performance-based, turnkey approach helps businesses uncover and correct overpayments across targeted operating expenses while minimizing the work required from internal teams.