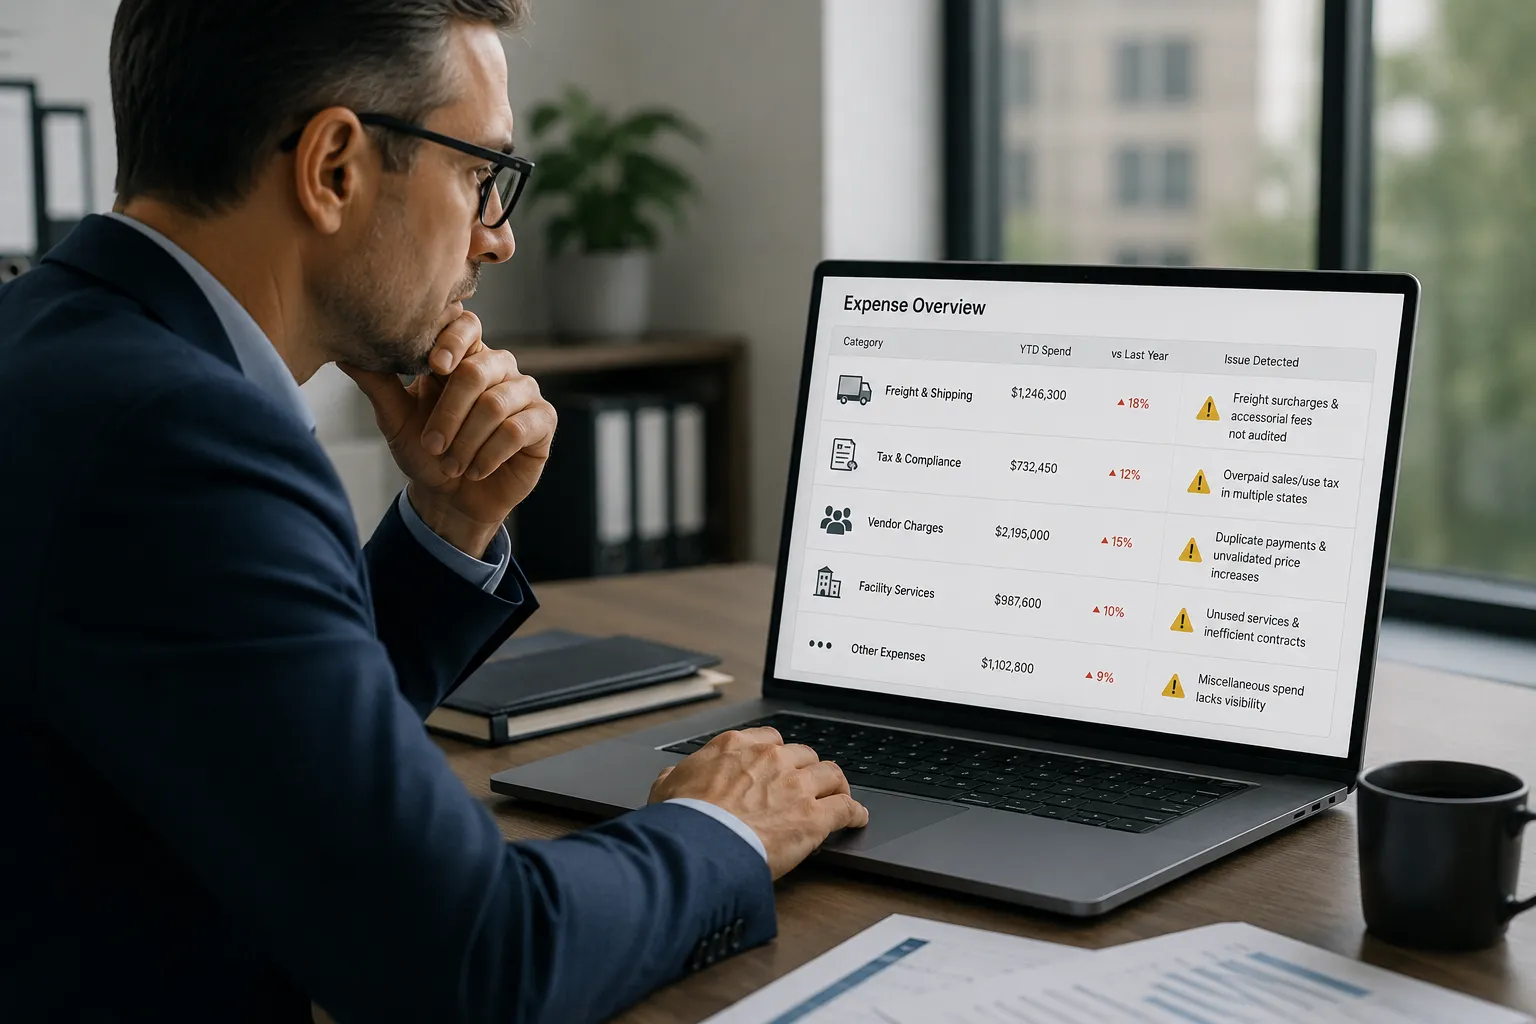
Every overlooked operating expense can chip away at manufacturing margins. Uncover hidden savings and strengthen your manufacturing cost reduction strategy.
Schedule a Free Cost Reduction Assessment
For manufacturers, margin leakage doesn’t always come from a major expense, which is why manufacturing cost reduction requires looking beyond the largest line items. It can start with a small freight surcharge, a missed Sales & Use Tax exemption, or a vendor renewal that quietly increases rates.
When these charges repeat across thousands of invoices, shipments, purchases, and recurring contracts, small overpayments can compound into meaningful losses. Deloitte’s 2024 MarginPLUS study found that 82% of companies fell short of their cost-reduction targets in 2024, up from 72% the previous year, highlighting how difficult it can be to turn planned savings into realized results.
These hidden costs can remain buried in routine operating expenses, making manufacturing cost reduction more difficult. APQC benchmarking data indicate that duplicate or erroneous payments can account for 0.8% to 2% of company disbursements, illustrating how seemingly minor errors can create significant leakage at scale.
Effective manufacturing cost reduction requires more than negotiating lower prices. For categories with complex pricing, contracts, or transaction-level charges, cost reduction services can provide the specialized analysis needed to identify opportunities internal teams may not have the capacity to investigate.
Finance and Procurement teams also need to identify money already lost, pursue legitimate cost recovery opportunities, and prevent unnecessary expenses from recurring.
This guide examines five areas where manufacturers commonly encounter hidden overpayments and where targeted manufacturing cost reduction efforts can uncover recoverable costs or ongoing savings:
- Sales & Use Tax Overpayments
- Freight & Parcel Billing Errors
- Waste Management Overpayments
- Merchant Services Fee Overcharges
- Uniform & Facility Service Overcharges
What is the difference between manufacturing costs and operating costs?
Manufacturing costs are expenses directly associated with producing goods, such as materials, labor, and production overhead. Operating costs support broader business activities outside production, including freight, facilities, waste management, and administrative expenses. Both can affect profitability, but manufacturing cost reduction requires different approaches for each.
1. Sales & Use Tax Overpayments
Manufacturers can overpay Sales & Use Tax when vendors apply tax incorrectly, eligible exemptions are missed, or changing rules affect how purchases should be taxed. This can affect purchases such as production equipment, materials, and other operational inputs, depending on their tax treatment and applicable exemptions. For multi-state manufacturers, differences in state requirements and high transaction volumes make these issues difficult to catch through routine AP processes, creating challenges for manufacturing cost reduction.
Why Does It Matter?
- Reclaims eligible tax overpayments through targeted cost recovery efforts
- Corrects tax treatment errors across transactions and multiple jurisdictions
- Identifies missed exemptions, credits, rebates, and other eligible tax recovery opportunities
- Strengthens visibility into recurring tax-related operating expenses
- Protects manufacturing margins from unnecessary tax-related financial leakage
Real-World Example: Midland Farms, a dairy processing and distribution company, discovered Sales & Use Tax paid in error on electricity. Its broader review identified $254,592.12 in savings, including recurring opportunities, refunds, and improved agreements.
Pro tip: Prioritize a Transactional Tax Refund Review when operations span multiple states, purchasing activity is substantial, or tax rules and exemptions change frequently. Reviewing historical transactions can help identify legitimate refund or credit opportunities that routine AP processes may have missed.
2. Freight & Parcel Billing Errors
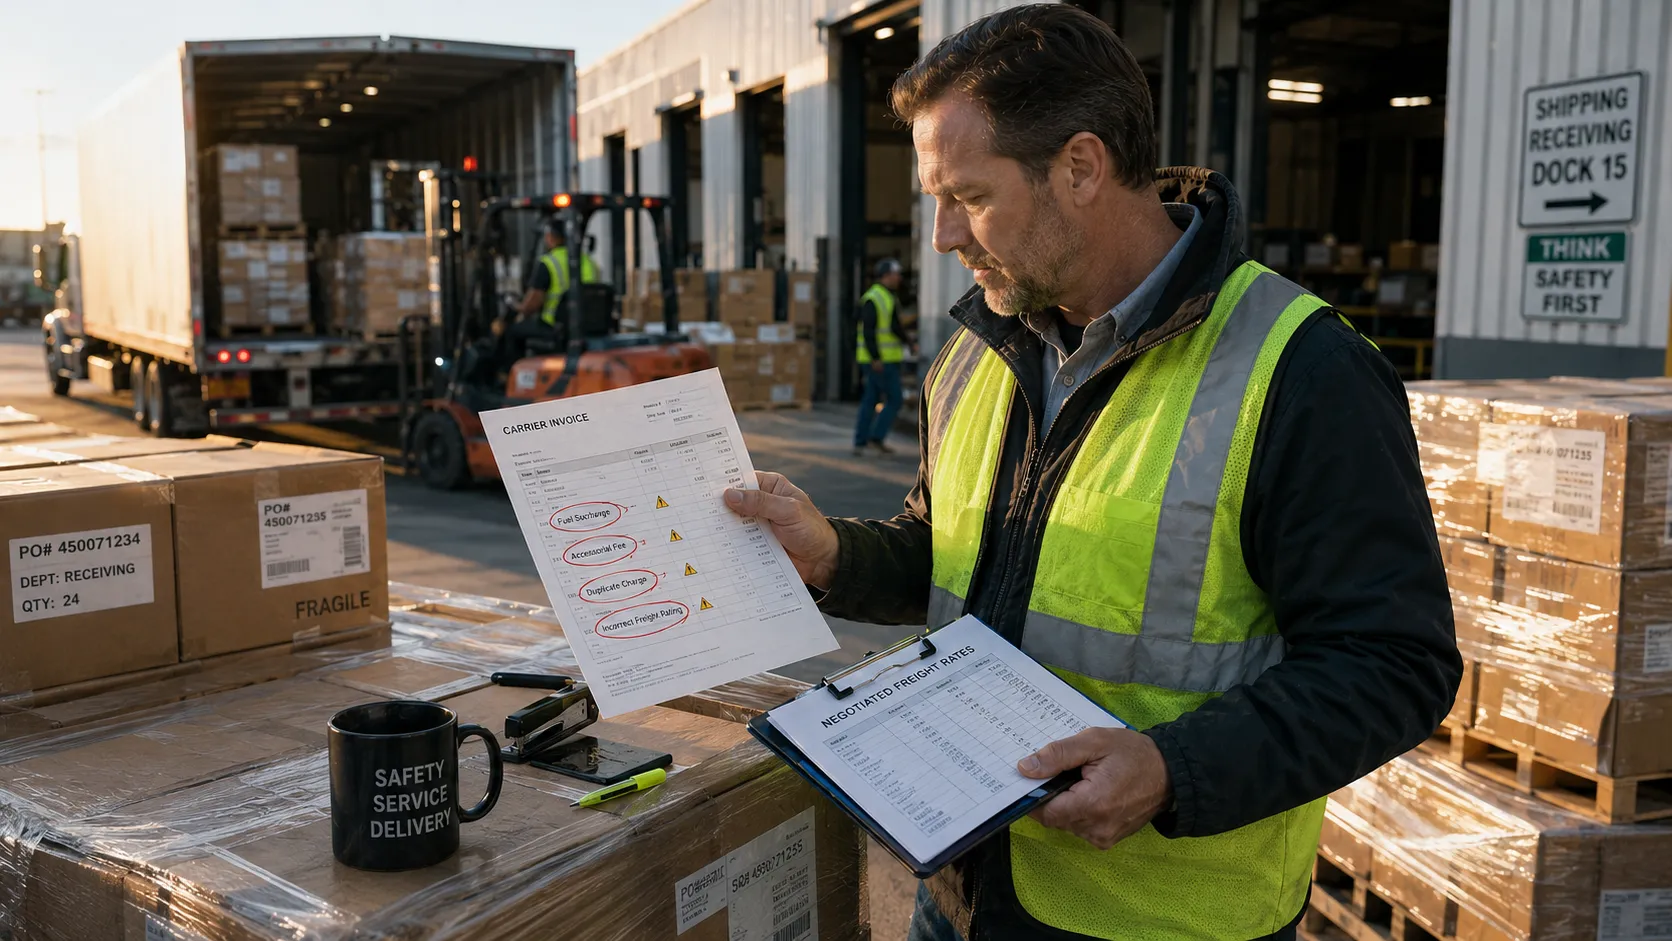
Freight and parcel overpayments can occur when invoices contain incorrect ratings, duplicate charges, fuel or accessorial surcharges, or pricing that differs from negotiated carrier rates. For manufacturers with high shipment volumes, even small discrepancies can accumulate across thousands of transactions.
Complex pricing structures can also make it difficult for internal teams to determine whether every charge accurately reflects the shipment, agreement, and applicable rates.
Separating these cost structures helps manufacturers identify discrepancies that can be hidden when transportation spend is reviewed as one category, strengthening manufacturing cost reduction efforts without relying solely on carrier negotiations.
Why does it matter?
- Lowers transportation costs without disrupting day-to-day shipment operations
- Confirms carrier charges match negotiated contract pricing and terms
- Limits surcharge exposure across recurring freight and parcel shipments
- Improves visibility into complex transportation spending patterns
- Enhances leverage during future carrier rate negotiations
Pro tip: Opt for a Freight & Parcel Expense Review to compare actual charges against negotiated carrier rates, contracts, and accessorial schedules to uncover pricing discrepancies and unnecessary fees. This is particularly useful when invoices contain numerous line-item charges, including fuel surcharges, dimensional weight, and other accessorial fees.
3. Waste Management Overpayments
Waste expenses can increase when contracted service levels no longer reflect a facility’s actual needs.
Changes in production volume, material handling, or facility operations can affect both the amount of waste generated and the equipment and pickup frequency required. When those operating conditions change without corresponding adjustments to contracted service levels, manufacturers may continue paying for capacity they no longer need.
Manufacturers may continue paying for oversized dumpsters, unnecessary pickups, excessive service frequency, or rates that have increased without a corresponding evaluation of the underlying service.
When services and pricing no longer reflect operational needs, manufacturers can lose opportunities for manufacturing cost reduction across recurring waste expenses.
Why does it matter?
- Eliminates unnecessary charges tied to excess service capacity
- Aligns service levels with actual facility requirements and waste volumes
- Controls recurring costs affected by contract rate increases
- Improves efficiency across facility-level waste spending
- Prevents outdated service terms from inflating ongoing operating expenses
Real-World Example: Newman Technology, an automotive parts manufacturer with 1,187 employees and $403 million in annual sales, reviewed its waste and other operating costs. The engagement identified $1,327,307.12 in savings, including recurring annual savings opportunities.
Pro Tip: Compare actual facility requirements with contracted waste services before renewing agreements or accepting rate increases. A Waste Management Expense Review can assess service levels, contracts, and market pricing to identify excessive spend and opportunities to right-size services.
4. Merchant Services Fee Overcharges
Merchant processing expenses can include complex statement-level fees, processing rates, interchange-related charges, and other pricing components that are difficult to evaluate through routine financial processes.
Manufacturers with substantial transaction volumes may continue with existing arrangements because payments process without disruption, even as costs gradually increase.
Over time, hidden fees and rate-related misspending can inflate payment processing expenses and create overlooked savings opportunities.
Why does it matter?
- Lowers payment processing costs through more competitive pricing
- Reveals fees that receive limited internal scrutiny
- Clarifies transaction costs across complex pricing structures
- Enhances leverage when negotiating provider rates
- Supports healthier margins across recurring payment activity
Real-World Example: Microflex, a manufacturing company with 90 employees and $27 million in annual sales, reviewed merchant card and other operating expenses. The engagement identified $752,346.60 in savings, including recurring annual savings opportunities.
Pro Tip: Benchmark statement-level processing fees and rates against competitive pricing structures before assuming an existing arrangement remains cost-effective. A Merchant Services Cost Review can examine merchant statements for hidden fees, rate discrepancies, and other recurring processing expenses.
5. Uniform & Facility Service Overpayments
Uniform and facility service costs can become misaligned as workforce levels, facility usage, service requirements, and contract terms change. Manufacturers may continue paying established rates or maintaining service levels simply because existing agreements remain in place.
Auto-renewals and contract escalators can increase costs even when the contracted service scope no longer matches current facility needs.
Why does it matter?
- Aligns recurring services with current operational requirements
- Limits unnecessary costs from outdated service levels
- Reduces exposure to contract-driven price increases
- Clarifies pricing across recurring service agreements
- Preserves savings as operational requirements change
The risk is not limited to price increases. A manufacturer may also be paying for service capacity, frequency, or scope that was appropriate when a contract was signed but no longer matches its current workforce, facility footprint, operating schedule, or usage. Reviewing both the commercial terms and the actual service requirements helps distinguish legitimate price changes from unnecessary recurring spend.
Pro tip: Reassess service levels, pricing, and contract terms before renewals, particularly after changes in facility usage, workforce size, or operational requirements. A Facilities Management Cost Review supports manufacturing cost reduction by identifying pricing discrepancies, excessive service scopes, and contract terms that no longer reflect current needs.
Can reducing operating costs improve manufacturing profit margins ?
Yes. Reducing unnecessary operating expenses can improve profit margins without requiring manufacturers to increase sales volume. This makes manufacturing cost reduction a practical lever for improving profitability without relying solely on revenue growth. Recovering past overpayments can provide a one-time benefit, while correcting recurring charges can create ongoing savings.
Which Operating Costs Should be Examined First for Manufacturing Cost Reduction ?
Manufacturers don’t need to scrutinize every operating expense with the same intensity. The strongest starting points are categories where high spend, recurring charges, complex pricing, or changing requirements make overpayments easier to miss.
The SALT Group has identified an average of $165K in recoveries per engagement, with potential recoveries reaching up to $1M depending on transaction history, spend volume, and multi-state exposure, highlighting the significant financial impact of addressing these overlooked areas.
| Overpayment Area | Why It Gets Overlooked | First Sign to Investigate | What to Check |
| Sales & Use Tax | Complex rules and multiple tax jurisdictions | Tax charges vary across similar purchases | Check tax treatment, exemptions, and credits across purchases and jurisdictions |
| Freight & Parcel | High transaction volumes and complex fee structures | Costs rise faster than shipment volumes | Compare invoice charges with contracted carrier rates and accessorial schedules |
| Waste Management | Services continue despite changing facility needs | Stable waste volumes with rising service costs | Compare actual waste volumes with contracted equipment and pickup frequency |
| Merchant Services | Processing remains operational despite changing fees | Processing costs rise without volume growth | Review statement-level rates and fees against current transaction volume and pricing terms |
| Uniform & Facilities | Contracts auto-renew as operational needs change | Recurring costs increase after renewals | Check current service scope, pricing, and renewal/escalator terms |
This gives Finance and Procurement teams a practical way to prioritize manufacturing cost reduction efforts, focusing limited review resources on categories where potential cost recovery or ongoing savings are most apparent.
When internal resources are limited, these warning signs can help Finance and Procurement teams determine where cost reduction services may warrant deeper consideration.
Build Stronger Margins Through Manufacturing Cost Reduction
Manufacturing cost reduction isn’t limited to production expenses or supplier negotiations. It also requires identifying operating-cost overpayments that can quietly weaken margins across recurring, high-volume spend categories.
Overpayments across taxes, freight, waste, merchant services, and facilities can quietly weaken manufacturing margins.
With 38+ years of experience and 5,000+ manufacturing clients served, The SALT Group brings specialized expertise to uncovering overpayments and reducing ongoing operating costs.
| Issue | What Happens | How SALT Helps |
| Sales & Use Tax | Missed exemptions, incorrect tax treatment, and changing state rules can lead to overpayments. | Reviews transactions to identify cost recovery opportunities, missed exemptions, credits, and incentives, backed by long-standing relationships with state tax authorities. |
| Freight & Parcel | Billing errors, surcharges, and pricing discrepancies can inflate shipping costs across high-volume shipments. | Reviews invoices, contracts, and carrier pricing to uncover overcharges and savings opportunities. |
| Waste Management | Outdated pickup schedules, equipment, or service levels can create unnecessary recurring costs. | Benchmarks services and pricing to right-size requirements and reduce ongoing spend. |
| Merchant Services | Complex rates and fees can increase processing costs without obvious changes in transaction volume. | Analyzes merchant statements to identify hidden fees, rate discrepancies, and savings opportunities. |
| Uniform & Facilities | Auto-renewals, escalators, and outdated service scopes can keep costs higher than necessary. | Reviews contracts, pricing, and service levels to identify excessive spend and optimize terms. |
SALT’s cost reduction services focus on a select set of high-impact spend categories where its consultants bring deep, category-specific expertise and independent benchmarking. Its turnkey approach manages the process from analysis through cost recovery and implementation, minimizing the time required from internal Finance and Procurement teams.
The model is performance-based: clients pay only when recoveries and/or savings are identified. This gives SALT a direct incentive to uncover every viable opportunity, from previously paid overpayments to recurring costs that can be reduced going forward.
Find out where your manufacturing operation may be overpaying and uncover opportunities for meaningful savings.
FAQs
1. Can manufacturers recover operating cost overpayments that have already been paid?
Yes. Eligible past overpayments may qualify for cost recovery, depending on the expense category, transaction history, contracts, applicable rules, and available documentation.
2. Will reviewing operating costs disrupt manufacturing operations or require major internal resources?
No. Reviews can use existing invoices, contracts, and financial records, minimizing demands on Finance and Procurement teams without disrupting day-to-day operations.
3. Does cost recovery require manufacturers to change vendors?
Not necessarily. Overpayments can often be addressed through billing corrections, contract adjustments, refunds, pricing changes, or service right-sizing while maintaining existing vendor relationships.
4. Are operating cost reviews worth pursuing if potential overpayments seem small?
Yes. Small discrepancies can become significant when repeated across thousands of invoices, shipments, transactions, or recurring contracts. Identifying them can uncover meaningful savings and support broader manufacturing cost reduction efforts.
5. When should manufacturers consider cost reduction services?
Manufacturers should consider cost reduction services when operating spend involves complex pricing, recurring charges, multiple vendors, changing service requirements, or categories where internal teams lack the time or specialized expertise to benchmark and investigate potential overpayments.
These services can be particularly useful when Finance and Procurement teams need category-specific analysis without taking on a large internal review workload.