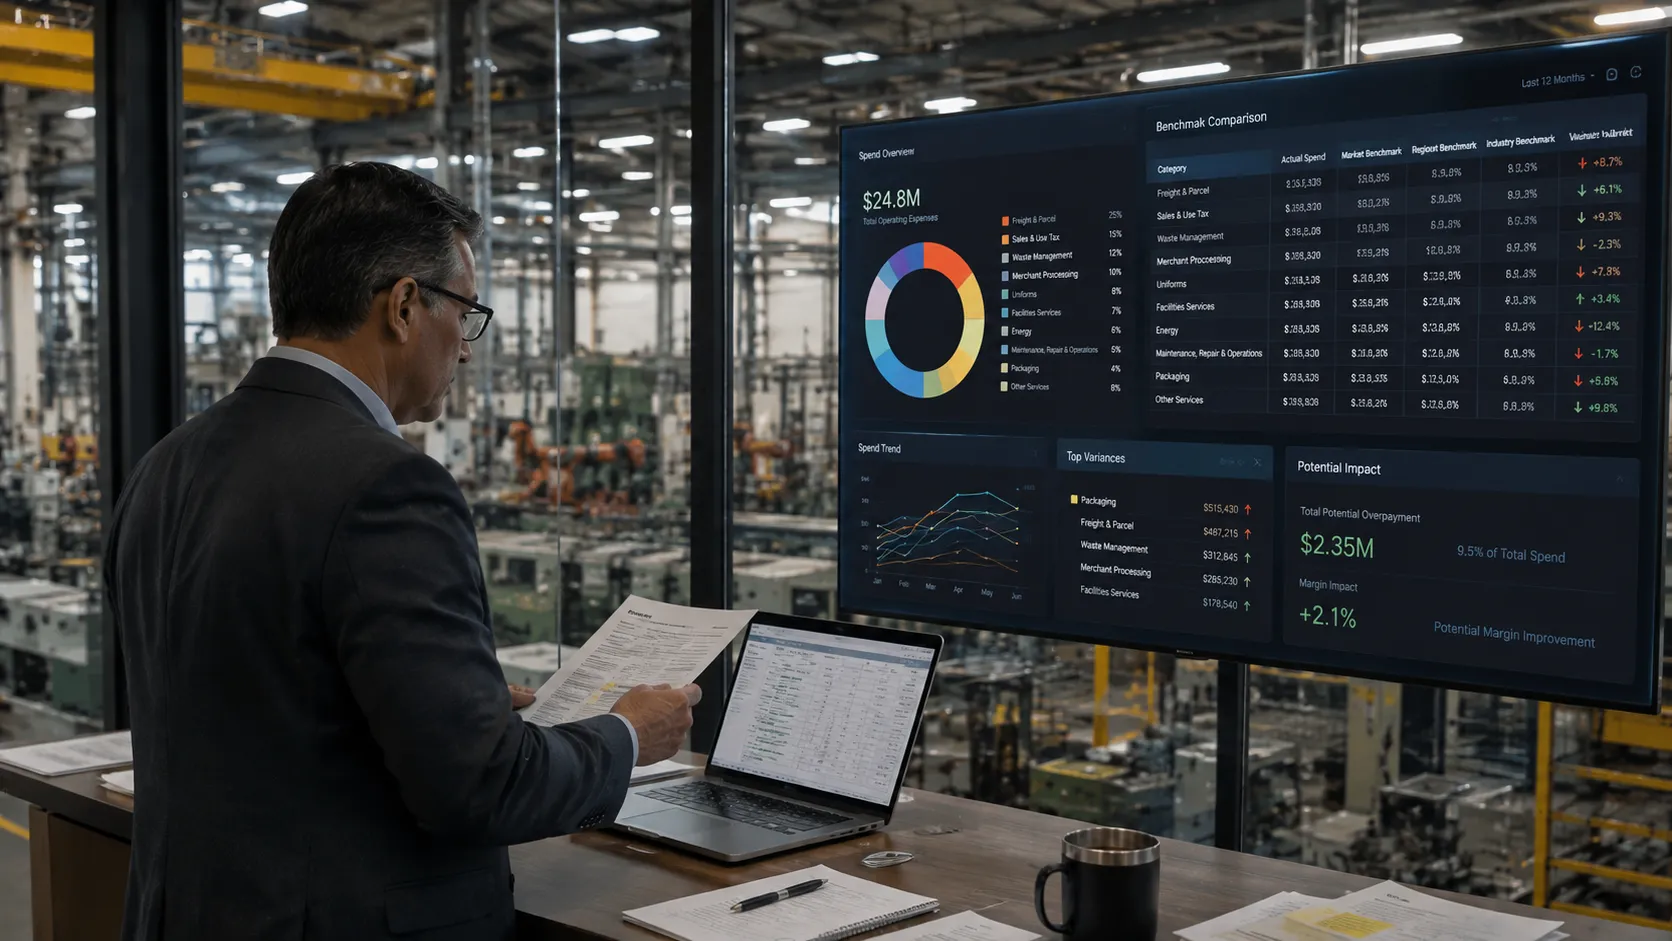
See how effective cost reduction strategies can help manufacturers focus resources on the highest-value opportunities and make more informed decisions about where to take action.
Executive Summary
What is operating expense benchmarking for manufacturers?
Operating expense benchmarking is the process of comparing what a manufacturer currently pays against relevant market, regional, industry, contractual, or service benchmarks to determine whether a cost warrants further investigation and supports informed cost reduction strategies. Benchmarking provides context for evaluating costs, but it does not by itself prove that a manufacturer has overpaid.
What does operating expense benchmarking examine?
Operating expense benchmarking examines actual charges alongside the factors that affect whether those costs are comparable, including volume, location, service scope, contract terms, and operational requirements. These factors help ensure manufacturers are making like-for-like comparisons and developing appropriate cost reduction strategies rather than treating every pricing difference as a potential overpayment.
What can manufacturers do with operating expense benchmarking findings
Manufacturers can investigate significant variances to determine their cause and validate whether they represent overpayments or other correctable issues. Confirmed findings can then support cost reduction strategies, including recovery efforts, pricing or contract changes, service adjustments, and other corrective actions that help prevent unnecessary costs from continuing.
What Is the Difference Between a Benchmark Finding and a Validated Opportunity?
A benchmark finding is a difference between a manufacturer’s cost and a relevant comparison that requires further explanation. It is not, by itself, proof of an overpayment.
A validated opportunity is a benchmark finding that has been investigated and supported by sufficient evidence to justify action through targeted cost reduction strategies. Depending on the cause, the appropriate response may include correcting a billing error, pursuing a recovery, renegotiating pricing, adjusting service levels, changing contract terms, or taking no action when the difference is justified.
Why Manufacturers Can’t Afford to Ignore Operating Expense Benchmarking
Cost pressure remains a strategic concern for manufacturers. Deloitte’s 2025 Global CPO Survey found that 72% of surveyed Chief Procurement Officers (CPOs) were focused on improving margins through cost reduction strategies, while 68% were focused on operational efficiency.
Operating expense benchmarking gives manufacturers a foundation for operating cost optimization by testing whether recurring costs still reflect current market conditions, operational needs, and contractual expectations. Without that context, pricing leakage can remain embedded in day-to-day spending through uncompetitive rates, outdated terms, unnecessary services, recurring fees, and overpayments that targeted cost reduction strategies can help address.
The following six blind spots show where financial risks typically emerge and which costs warrant closer investigation. To benchmark costs against industry standards, manufacturers should compare like-for-like operating expenses across relevant regions, operating conditions, service requirements, and transaction volumes.
1. Limited Market Context Can Hide Uncompetitive Costs
Finance teams may know exactly what they pay without having reliable external context for determining whether those costs remain competitive. Internal records show historical spending, but they cannot independently show how pricing compares with relevant market, regional, or industry conditions.
Effective expense benchmarking gives Finance and Procurement teams external context for evaluating whether established pricing still reflects market conditions. Relevant cost savings benchmarks can help identify opportunities for targeted cost reduction strategies.
- Compare internal costs with relevant external benchmarks.
- Challenge pricing that no longer reflects current market conditions.
- Apply category-specific market intelligence where appropriate.
- Identify material differences that warrant further investigation.
Without market context, manufacturers can continue paying above-market rates simply because there is no objective basis for challenging them.
2. Supplier Reliability Can Create Pricing Assumptions
Long-standing suppliers may continue delivering reliable service while their pricing gradually becomes less competitive. When performance remains acceptable, manufacturers may assume the commercial arrangement remains reasonable without reassessing whether rates, fees, or terms still reflect available market value.
PwC’s Pulse Survey found that 65% of business executives were renegotiating supplier pricing or planned to do so, reflecting growing pressure to protect margins as input costs change.
Objective benchmark data can help manufacturers pursue cost reduction strategies by supporting discussions with existing suppliers about pricing, service scope, and contract terms, without automatically requiring a vendor change.
- Review supplier pricing against relevant alternatives.
- Reassess commercial arrangements as business requirements change.
- Evaluate whether existing agreements still provide competitive value.
- Strengthen negotiation leverage with current pricing intelligence.
3. Transaction-Level Leakage Can Accumulate Across Recurring Spend
Small discrepancies rarely create immediate concern when viewed individually. A minor surcharge, billing inconsistency, or pricing difference can appear immaterial on one invoice but become financially significant when repeated across thousands of transactions, locations, or billing cycles. This is one way price leakage can affect manufacturing operations.
A detailed billing review can compare invoice charges with negotiated rates, contractual terms, service records, and actual transaction activity. This helps manufacturers identify duplicate charges, incorrect rates, unexplained surcharges, and recurring discrepancies that may otherwise go unnoticed during routine accounts payable processing.
- Calculate the cumulative impact of recurring discrepancies.
- Trace repeated issues across transactions and locations.
- Examine high-volume categories for transaction-level leakage.
- Prioritize patterns capable of creating material financial impact.
Detailed operating expense analysis and invoice comparisons can reveal how small recurring charges accumulate into substantial unnecessary spending and potential recovery opportunities.
4. Geographic Variation Can Make Simple Comparisons Misleading
Costs vary across regions because of local market conditions, facility requirements, labor, service availability, transaction volume, and other operational factors. A rate that appears high in one location may be reasonable, while a seemingly standard rate elsewhere may be uncompetitive.
- Account for geographic differences when comparing costs.
- Compare expenses against relevant regional and industry benchmarks.
- Adjust comparisons for facility size and service requirements.
- Use genuinely comparable operations as reference points.
Comparing costs without geographic context can cause manufacturers to miss genuine overpayments or challenge legitimate costs incorrectly, making their cost reduction strategies less effective.
5. Outdated Contracts Can Lock In Unnecessary Costs
A contract can remain fully compliant while no longer serving the manufacturer’s current needs. Automatic escalators, renewal increases, legacy service levels, and outdated purchasing assumptions can keep unnecessary costs embedded in operating expenses long after the original arrangement made sense.
- Review automatic increases before they become embedded costs.
- Reassess legacy terms against current operating requirements.
- Verify that contracted services still match actual needs.
- Challenge renewal pricing that lacks current market support.
Manufacturers can continue paying for outdated pricing or unnecessary services even when every invoice technically matches the contract.
6. Uninvestigated Variances Can Become Missed Recovery Opportunities
Identifying an unusual cost is only the first step. A meaningful variance must be investigated to determine whether it reflects a legitimate business difference, a billing issue, an overpayment, or another correctable problem.
- Quantify the potential financial impact of identified variances.
- Investigate the causes behind material differences.
- Assess whether historical overpayments may be recoverable.
- Address issues that could continue generating unnecessary costs.
When manufacturers stop at identifying a variance, they can miss opportunities to recover past overpayments and use cost reduction strategies to prevent the same leakage from continuing.
The real risk isn’t knowing what your operating expenses are. It’s assuming they’re reasonable simply because they’ve always been paid.
How do you calculate operating costs for a manufacturing business?
Manufacturers typically calculate operating costs by totaling the expenses required to run the business outside directly attributable production costs, using the company’s accounting definitions and reporting structure. Finance can then organize those operating expenses by category, location, volume, or other relevant cost drivers for benchmarking.
How The SALT Group’s Operating Expense Benchmarking Framework Works
Not every cost difference indicates an overpayment. For example, a higher Freight & Parcel cost may reflect a longer shipping distance or faster service level, while higher Waste costs may result from local disposal requirements or more frequent pickups. Uniforms & Facilities costs may also differ because of workforce size or facility usage. These differences need to be evaluated in context rather than treated as evidence of supplier overcharging.
The SALT Group’s Operating Expense Benchmarking Framework uses a consistent six-stage process to guide manufacturing cost reduction strategies. This structured approach to OPEX reduction consulting helps manufacturers identify cost variances, validate findings, and prioritize corrective action.
The six stages are to benchmark tax treatment, compare freight and parcel rates, review waste pricing, analyze merchant services, evaluate uniforms and facilities, and prioritize validated recovery opportunities. Together, they help manufacturers distinguish legitimate cost differences from issues that warrant investigation, recovery, or corrective action.
The framework is applied across six core areas:
- Step 1: Benchmark Sales & Use Tax
- Step 2: Compare Freight & Parcel Rates
- Step 3: Review Waste Pricing
- Step 4: Analyze Merchant Services
- Step 5: Evaluate Uniforms & Facilities
- Step 6: Prioritize Recovery Opportunities
Step 1: Benchmark Sales & Use Tax
Benchmark tax treatment across similar purchases, jurisdictions, locations, and reporting periods, including applicable rates, exemptions, and credits. This analysis can identify unusual or potentially incorrect tax costs and inform targeted cost reduction strategies, but it does not establish that an overpayment is recoverable.Differences may indicate inconsistent treatment, a missed exemption, or a vendor charging error.
- Map tax exposure: Identify differences in tax treatment across jurisdictions, purchase types, and locations.
- Verify exemptions: Confirm whether qualifying purchases received applicable exemptions, credits, or other favorable treatment.
- Trace transaction patterns: Review comparable purchases across facilities and reporting periods for recurring discrepancies.
- Validate differences: Determine whether unusual tax charges reflect legitimate requirements or validated recovery opportunities.
Step 2: Compare Freight & Parcel Rates
Benchmark shipment charges, negotiated carrier rates, contract terms, and surcharges across comparable shipment profiles. Differences can reveal billing discrepancies, uncompetitive rates, excessive surcharges, or outdated contract terms. Deloitte’s 2025 Manufacturing Industry Outlook reported that more than 35% of surveyed manufacturers cited transportation and logistics costs as a primary business challenge in Q3 2024.
Manufacturers should normalize shipments for weight, dimensions, distance, destination, service level, and carrier before investigating differences and validating charges against negotiated terms. This process can help identify freight overpayments that may warrant recovery or other corrective action as part of broader cost reduction strategies.
- Normalize shipment data: Account for weight, dimensions, distance, destination, service level, and carrier.
- Match contract terms: Reconcile invoice charges with negotiated carrier rates.
- Trace surcharge activity: Isolate fuel, dimensional, accessorial, and other fees contributing to transportation costs.
- Compare carrier pricing: Assess comparable shipment charges across carriers, locations, and periods to inform cost reduction strategies.
What factors should be considered when benchmarking freight costs?
Freight benchmarking should account for shipment weight, dimensions, distance, destination, service level, carrier, fuel and accessorial surcharges, and negotiated contract rates. Comparing shipments without these variables can create misleading variances because a higher charge may reflect materially different transportation requirements.
Step 3: Review Waste Pricing
Benchmark waste volumes, pickup frequency, container capacity, actual utilization, and pricing against facility requirements and relevant local market conditions. Discrepancies can reveal oversized containers, pickups scheduled more often than necessary, underused capacity, outdated service arrangements, excessive fees, or uncompetitive pricing.
Compare actual waste generation and container utilization with contracted capacity and pickup schedules to determine whether services are right-sized, then investigate material gaps and apply appropriate waste management cost reduction strategies where warranted.
- Measure waste volumes: Compare actual disposal volumes with contracted container capacity and pickup frequency.
- Assess utilization: Determine whether containers are consistently underused, full before scheduled pickups, or appropriately sized.
- Right-size service levels: Adjust container capacity and pickup schedules to match actual waste generation and facility needs.
- Test regional pricing: Evaluate current rates against relevant local market conditions and comparable arrangements.
- Flag unnecessary charges: Identify additional fees or services that no longer align with operational needs.
Step 4: Analyze Merchant Services
Benchmark total processing costs, effective rates, transaction profiles, and fee structures against relevant pricing arrangements and comparable transaction activity. A low headline rate does not necessarily mean lower overall costs: processor, transaction, assessment, and recurring fees can materially increase the effective rate. Differences may reveal changes in transaction mix, unnecessary charges, unexplained increases, or uncompetitive fee structures.
A detailed operating expense analysis should examine the total cost of payment processing rather than relying on a single advertised rate, providing a stronger basis for cost reduction strategies in merchant services.
- Calculate effective rates: Divide total processing costs including all applicable fees by transaction volume to measure the actual cost of payment acceptance.
- Break down fees: Trace processor, transaction, assessment, and recurring charges that may increase total costs beyond the headline rate.
- Compare pricing structures: Assess total effective costs against relevant alternatives and comparable transaction profiles.
- Spot unexplained increases: Investigate processing costs that rise without corresponding changes in transaction activity.
How do you compare merchant service fees between providers?
Compare merchant service providers using effective cost rather than a single advertised rate. Calculate total processing fees against transaction volume, then account for processor charges, assessment fees, transaction fees, recurring charges, pricing structure, and transaction mix to make the comparison meaningful.
Step 5: Evaluate Uniforms & Facilities
Benchmark Uniforms & Facilities contracts, pricing, workforce requirements, facility usage, and renewal terms against current operational needs and relevant market conditions. Gaps can reveal unnecessary services, outdated service levels, automatic escalators, renewal increases, or pricing that no longer reflects current requirements.
Manufacturers should reconcile Uniforms & Facilities with actual needs, investigate material gaps, and determine whether service, contract, or pricing changes are warranted as part of their cost reduction strategies.
- Reconcile service scope: Compare contracted uniform and facility services with current workforce, facility usage, and operational requirements.
- Track pricing changes: Identify escalators, renewal increases, and other adjustments affecting recurring costs.
- Compare location spend: Assess comparable Uniforms & Facilities across facilities to identify differences requiring explanation.
- Challenge outdated terms: Reassess provisions that may no longer reflect current service needs or market conditions.
Step 6: Prioritize Recovery Opportunities
Evaluate validated findings based on financial impact, recurrence, scope, potential recoverability, and the strength of available evidence to prioritize the most significant opportunities that can inform manufacturing cost reduction strategies. Significant differences may indicate historical overpayments, ongoing unnecessary spending, or correctable contractual, pricing, or operational issues.
Once a finding has been validated, determine the appropriate cost reduction strategies based on its cause. Cost recovery consulting may help manufacturers assess substantiated historical overpayments and establish whether recovery is an appropriate course of action.
- Billing error: Correct the charge and pursue recovery of validated vendor overpayments where appropriate.
- Contract mismatch: Reconcile the charge with the agreed terms and address the discrepancy.
- Uncompetitive pricing: Use the evidence to support renegotiation or evaluate alternatives.
- Excess or unnecessary service: Adjust service levels or scope to match actual requirements.
- Tax treatment issue: Investigate applicable requirements and pursue correction or recovery where supported.
- Legitimate variance: Document the explanation and take no corrective action when the cost is justified.
Prioritize issues with the greatest financial impact, recurrence, supporting evidence, recoverability, and risk of continued leakage when applying cost reduction strategies.
What should manufacturers do after validating a variance?
A benchmark finding is a difference that requires explanation, not proof of an overpayment or savings opportunity. Manufacturers should investigate the cause and validate whether the difference is justified by legitimate operating factors. Once the cause is confirmed, the appropriate response may be to take no action, correct billing, pursue recovery, renegotiate pricing or contract terms, adjust unnecessary services, or monitor the category for future changes.
The table below brings the framework’s category-specific benchmarking methodology into one view.
The SALT Group’s Operating Expense Benchmarking Framework at a Glance
The SALT Group applies specialized category expertise to evaluate complex operating expenses, investigate pricing and billing discrepancies, and distinguish legitimate cost differences from validated recovery opportunities and other cost reduction strategies.
This expertise supports a structured methodology for moving from benchmark comparisons to validation, prioritization, and appropriate recovery or corrective action.
| Stage | What You Do | Outcome |
| Benchmark Tax | Compare tax treatment across purchases and jurisdictions; investigate unusual charges and exemptions. | Potentially incorrect tax costs are identified and validated before recovery or corrective action is pursued. |
| Compare Freight | Normalize shipment costs and validate charges against negotiated terms. | Pricing differences are explained as legitimate operating factors or identified for further investigation. |
| Review Waste | Compare waste volumes, utilization, container capacity, pickup frequency, and pricing against actual facility needs. | Oversized services, unnecessary pickups, or pricing gaps are identified for right-sizing or further review. |
| Analyze Merchant Services | Evaluate total processing costs and effective rates, including transaction, processor, assessment, and recurring fees. | The true cost of payment processing is established, revealing whether pricing differences warrant correction. |
| Evaluate Uniforms & Facilities | Assess contracted Uniforms & Facilities, pricing, usage, workforce requirements, and renewal terms against current needs. | Outdated services, unnecessary costs, or contract gaps are identified for investigation and potential changes. |
| Prioritize Recovery | Rank validated findings by financial impact, recurrence, evidence, recoverability, and time sensitivity. | Manufacturers focus first on opportunities with the strongest case for recovery, correction, or preventing continued leakage through targeted cost reduction strategies. |
The framework gives manufacturers a consistent way to evaluate operating expense differences in the context of geography, volume, service requirements, contract terms, and operating conditions. These insights help inform their cost reduction decisions.
What is the difference between a benchmark finding and a validated opportunity?
A benchmark finding flags a difference worth explaining, while a validated opportunity is one that has been investigated and supported by sufficient evidence to justify action. That action may involve correcting billing, pursuing recovery, renegotiating terms, adjusting services, or taking no action if the difference is justified.
What Happens When Manufacturers Challenge Their Operating Expenses
Two manufacturers can face similar cost pressures yet experience different financial outcomes. The difference often comes down to how closely they scrutinize the operating expenses embedded in their day-to-day operations and whether they act on the findings through relevant manufacturing cost reduction strategies.
Good Example: Apex Manufacturing Finds What Routine Reviews Missed
Apex Manufacturing, a multi-location manufacturer, had no obvious billing crisis, but recurring costs across its facilities were becoming increasingly difficult to evaluate. Instead of assuming that established supplier costs were reasonable, the company reviewed freight, waste, merchant services, and facility services against invoices, contracts, and relevant market benchmarks to develop targeted manufacturing cost reduction strategies.
A hypothetical 3% variance across $2.4 million in annual spending in these categories could represent approximately $72,000 in potential excess costs. This is an illustrative calculation only, not documented savings or an actual recovery result.
The review helped Apex identify which recurring costs deserved attention and prioritize practical cost reduction strategies while minimizing the effort required from its Finance and Procurement teams.
Bad Example: Northstar Manufacturing Pays for Leaving Operating Expenses Unchallenged
Northstar Manufacturing produces components across several U.S. facilities and has relied on the same vendor rates for years. Because invoices matched contractual terms and suppliers continued meeting service expectations, Finance assumed the pricing remained competitive and saw little reason to benchmark it.
In this illustrative scenario, benchmarking comparable pricing identified a difference that warranted further investigation. That difference alone did not prove an overpayment, so Northstar would need to examine whether geography, volume, service requirements, contract terms, or operating conditions justified the pricing.
If the difference remained unexplained after investigation, Northstar could determine whether corrective cost reduction strategies were warranted. Without external benchmarks to challenge established rates, however, the company had limited visibility into whether long-standing pricing remained competitive or whether recurring costs required attention.
Takeaway: Both scenarios show that accurate financial records do not necessarily reveal whether operating expenses remain competitive or require attention. Relevant benchmarks and independent analysis can help manufacturers distinguish justified differences from issues that warrant corrective action through cost reduction strategies.
Best Practices for Maximizing Operating Expense Benchmarking Results With Effective Cost Reduction Strategies
Effective benchmarking supports cost reduction strategies by helping manufacturers prioritize findings, use objective data in supplier discussions, and reassess costs as business or market conditions change.
Pro Tip 1: Rank Findings Before Investigating Everything
Not every benchmark variance deserves the same level of attention when evaluating potential cost reduction strategies. Rank findings by financial value, frequency, scope, and the likelihood of recovery or cost reduction before committing internal resources to a deeper review.
Prioritizing findings this way helps manufacturers focus first on discrepancies with the greatest potential financial impact, recurring exposure, and practical opportunity for corrective action.
Pro Tip 2: Use Benchmark Findings to Strengthen Supplier Conversations
Expense benchmarking can provide independent evidence to support supplier-focused cost reduction strategies. Rather than requesting general price reductions, manufacturers can use documented differences in pricing, service scope, market conditions, or contract terms to make supplier discussions more specific.
For example, McKinsey has documented a case where a company replaced its majority services vendor with a minority supplier after a structured negotiation process, reducing costs by more than 30%. This is a case-specific outcome, not a typical or guaranteed result, but it demonstrates how stronger cost intelligence can improve negotiating leverage.
Pro Tip 3: Rebenchmark When the Business or Market Changes
Benchmarking should not be treated as a one-time exercise because effective cost reduction strategies require periodic reassessment. Previously appropriate pricing can become less competitive when suppliers change, contracts renew, facilities are acquired, volumes shift significantly, or market conditions change.
Manufacturers should establish a regular review cadence for high-value or frequently recurring expense categories and trigger additional reviews after major business or market changes. This helps ensure established arrangements continue to reflect current requirements rather than becoming the default simply because they have existed for years.
The SALT Group’s Operating Expense Benchmarking Framework provides the analytical process, while these cost reduction strategies show manufacturers how to act on its findings through prioritization, supplier discussions, and ongoing review.
Common Operating Cost Benchmarking Mistakes That Limit Savings
Operating expense benchmarking can produce misleading conclusions when manufacturers compare the wrong costs, rely on incomplete pricing information, or assume that every variance represents an overpayment.
These mistakes can distort the analysis, undermine cost reduction strategies, and divert attention toward differences with legitimate explanations. Avoiding them helps manufacturers make relevant comparisons, evaluate total costs accurately, and focus investigations on findings that deserve closer review.
| Common Mistakes | What You Should Do |
| Treating every variance as an overpayment | Investigate the cause before taking action. Differences may be justified by contract terms, geography, volume, service requirements, or operating conditions. |
| Using an inappropriate benchmark | Compare genuinely similar costs by accounting for geography, volume, service scope, supplier type, and operating conditions. |
| Evaluating unit price instead of total cost | Assess the full cost of the arrangement, including fees, surcharges, utilization, service levels, recurring charges, and total transaction costs. |
| Assuming contract compliance means competitive pricing | Benchmark established rates periodically to determine whether contractual pricing still reflects current market conditions and operational needs. |
| Investigating every difference with equal priority | Focus first on findings with the greatest financial value, frequency, scope, supporting evidence, and likelihood of recovery or cost reduction. |
Effective benchmarking requires relevant comparisons, a complete view of total costs, and enough context to explain why differences exist and support evidence-based cost reduction strategies.
Operating Cost Benchmarking Checklist
An operating expense benchmarking review is only useful if findings can move from analysis to action. Use this checklist to confirm that the right data has been gathered, costs have been compared on a like-for-like basis, findings have been properly validated, and agreed actions are not lost after the initial review.
| Checklist | |
| ☐ | Have we defined the specific cost category and expenses being reviewed? |
| ☐ | Is the benchmark relevant to our geography, volume, service scope, supplier type, contract terms, and operating conditions? |
| ☐ | Are we comparing genuinely similar transactions, services, or operational requirements? |
| ☐ | Do we have the necessary invoices, contracts, transaction records, and service data to investigate identified differences? |
| ☐ | Have we considered legitimate factors that could explain a benchmark variance before treating it as a potential overpayment? |
| ☐ | Has an owner been assigned to investigate each material variance? |
| ☐ | Have findings been ranked by financial value, frequency, scope, and likelihood of recovery or cost reduction? |
| ☐ | Has each validated finding been assigned a clear next action, such as recovery, renegotiation, service changes, or contract adjustments? |
| ☐ | Are actions, owners, timelines, and outcomes being tracked through completion? |
| ☐ | Have we established when the category should be benchmarked again or identified triggers such as supplier changes, contract renewals, acquisitions, significant volume changes, or market shifts? |
The checklist is not simply about completing a one-time review. Its value comes from helping manufacturers apply consistent cost reduction strategies by validating findings, tracking corrective action, and revisiting costs when business or market conditions change.
Identify Where Your Manufacturing Operations May Be Overpaying
Manufacturers need more than benchmarks to reduce operating expenses effectively. They need structured cost reduction strategies that help distinguish legitimate cost differences from variances requiring investigation or corrective action.
The SALT Group’s Operating Expense Benchmarking Framework helps manufacturers apply cost reduction strategies by benchmarking operating expenses, investigating potential overpayments, and identifying opportunities across major spend categories, including freight, merchant services, waste management, and facilities.
Its category-specific expertise and coordinated, turnkey review process help manufacturers address complex expense areas without requiring internal Finance and Procurement teams to manage every investigation themselves. A dedicated client manager helps coordinate the engagement and reduce the workload on internal teams. Its performance-based model aligns the engagement with identified benefits.
For manufacturers seeking cost reduction strategies, this combination of specialized expertise, category-specific analysis, turnkey execution, and performance-based engagement offers a practical way to address operating expenses that might otherwise go unchallenged.
Find out where your manufacturing operations may be overpaying. The SALT Group can help benchmark operating expenses, investigate potential overpayments, and evaluate opportunities to reduce unnecessary operating expenses across major spend categories.
FAQs
Q1. Do I need cost benchmarking if my Finance team already reviews contracts and invoices regularly?
Yes. Internal reviews can confirm whether invoices match agreed terms, but they may not show whether those terms remain competitive as market conditions, volumes, or operating requirements change. Cost reduction strategies informed by independent market and category expertise can complement existing Finance controls, helping teams decide which established costs deserve a closer review without replacing routine invoice or contract management.
Q2. Will cost reduction consulting require significant time or resources from my Finance and Procurement teams?
Not necessarily. The level of internal involvement depends on the scope of the review and the availability of supporting records. A turnkey cost reduction consulting engagement can reduce the burden by having specialists manage much of the data analysis, investigation, and follow-through while Finance and Procurement provide the necessary documentation and business context.
Q3. How do I know whether a pricing variance is a legitimate difference or an actual overpayment?
The key question is whether the difference remains after relevant operating factors have been considered. Geography, volume, service requirements, contract terms, and transaction characteristics may justify different pricing. Manufacturers should validate the underlying cause using supporting records before deciding whether to take no action, make a contract or service change, or pursue potential recovery. Evidence-based cost reduction strategies should follow this validation rather than precede it.
Q4. Does operating cost benchmarking require us to change suppliers?
No. A benchmark finding does not automatically mean a supplier relationship should end. The results may support renegotiating pricing, correcting billing, adjusting service levels, or updating contract terms while keeping the existing supplier. These actions can form part of cost reduction strategies that address unnecessary expenses without disrupting an established supplier relationship. Changing suppliers may be considered only when the current arrangement cannot reasonably meet the manufacturer’s cost, service, or operational requirements.
Q5. How much historical data do manufacturers need for an operating cost benchmark?
The amount of historical data required depends on the expense category and the stability of the underlying activity. Manufacturers generally need enough historical data to identify recurring patterns, account for seasonal or operational changes, and make meaningful comparisons. For highly variable costs, a longer period may provide better context, while stable recurring expenses may require less history. Available contract dates, pricing changes, and transaction records should also guide the review period and help ensure that any resulting cost reduction strategies are based on reliable comparisons.
Q6. How often should I benchmark operating costs to prevent overpayments from returning?
There is no single schedule that applies to every expense category. Higher-value, volatile, or frequently recurring costs may warrant more regular reviews, while other categories can be reassessed when a contract approaches renewal or operating conditions change. Manufacturers should also establish triggers, such as significant volume shifts, facility changes, supplier increases, or new contract terms, that prompt a review before costs become embedded in ongoing spend. Incorporating these reviews into ongoing cost reduction strategies can help manufacturers identify and address emerging overpayments.
Related Articles
Research & References
- Deloitte’s 4 Ways to Reshape Procurement to Enhance Business Value
- Deloitte’s 2025 Manufacturing Industry Outlook
- McKinsey’s Case Studies
- PwC’s Pulse Survey: 100 Days In: What’s Next for Business